Choosing the right credit card can feel overwhelming. Walk into any bank or open any comparison website, and you’ll find dozens of options, each promising cash back, travel perks, low interest rates, or credit-building power. But not every card is designed for the same purpose, and picking the wrong one can cost you money in fees and missed rewards.
This guide breaks down the main types of credit cards available today, explains how each one works, and helps you figure out which type actually fits your financial situation and goals.
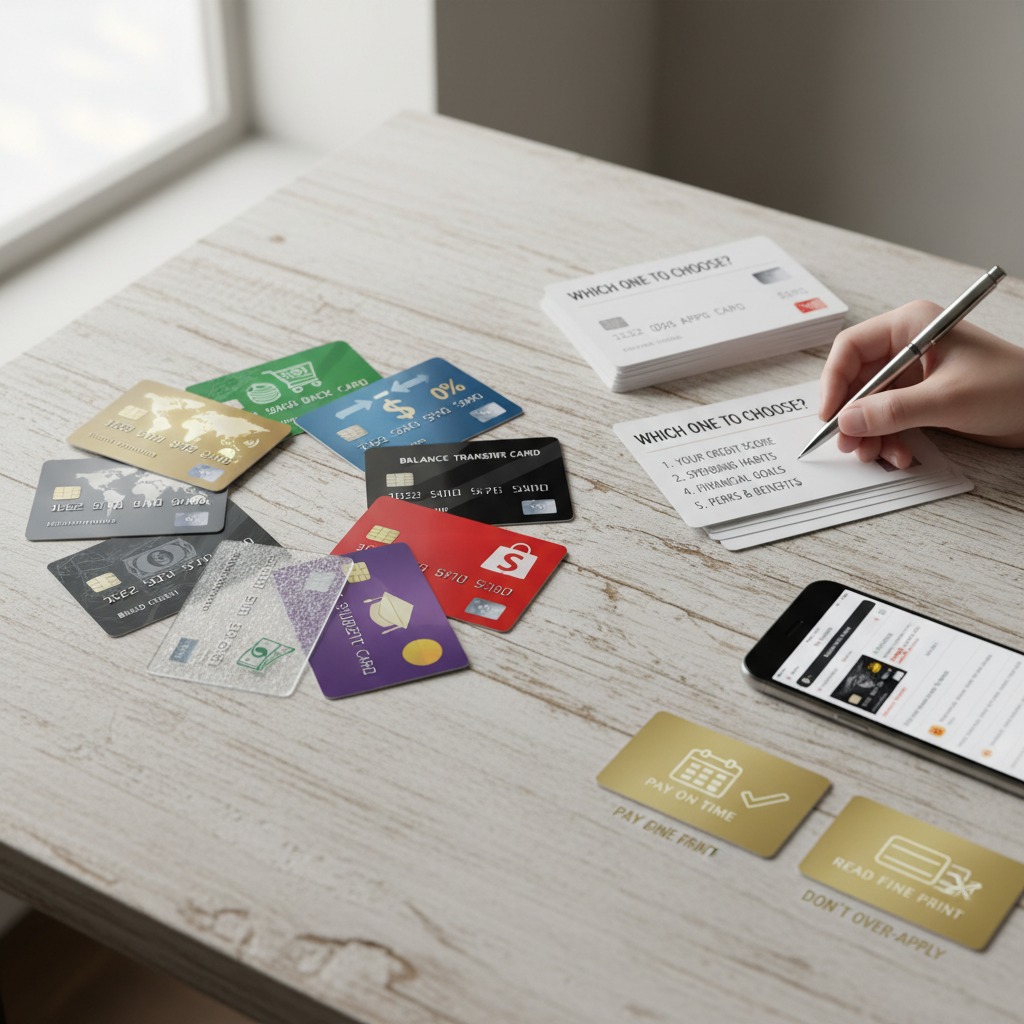
Why the Type of Credit Card You Choose Matters
Before comparing specific cards, it helps to understand that credit cards aren’t one-size-fits-all products. Some are built to reward frequent spending, others to help you pay off debt, and others simply to help you build or repair credit history. Choosing a card based on its type — rather than just its advertised rewards — is the first step toward using credit responsibly and getting real value from it.
With that in mind, let’s look at the most common categories of credit cards.
1. Rewards Credit Cards
Rewards cards let you earn points, miles, or cash back on your everyday purchases. They’re popular because they turn regular spending into tangible benefits, but they usually require good to excellent credit to qualify, and many charge higher interest rates if you carry a balance.
Best for: People who pay their balance in full each month and want to earn something extra from spending they’d do anyway.
Watch out for: Annual fees that can outweigh the rewards if you don’t spend enough to justify them.
2. Cash Back Credit Cards
A subcategory of rewards cards, cash back cards return a percentage of your spending directly to you, either as statement credit, a bank deposit, or a check. Some offer a flat rate on all purchases, while others offer higher percentages in specific categories like groceries, gas, or dining, often on a rotating quarterly basis.
Best for: People who want straightforward, easy-to-understand rewards without dealing with point conversion charts or travel booking portals.
Watch out for: Category caps and spending limits that reduce your cash back rate once you exceed a certain threshold.
3. Travel Credit Cards
Travel cards are designed for people who fly or stay in hotels frequently. They typically earn miles or points redeemable for flights, hotel stays, or travel-related purchases, and many come with added perks such as airport lounge access, free checked bags, or travel insurance.
Best for: Frequent travelers who can make the most of sign-up bonuses and travel-specific perks.
Watch out for: Foreign transaction fees on non-travel cards, and annual fees that only pay off if you actually use the travel benefits.
4. Low-Interest and 0% APR Credit Cards
These cards are built around minimizing the cost of borrowing rather than maximizing rewards. Many offer an introductory 0% Annual Percentage Rate (APR) period on purchases, balance transfers, or both, which can last anywhere from several months to over a year, depending on the issuer.
Best for: People planning a large purchase they’ll pay off over time, or anyone looking to transfer existing high-interest debt to reduce what they pay in interest.
Watch out for: The regular APR that kicks in once the introductory period ends — if you still carry a balance at that point, interest charges can add up quickly.
5. Balance Transfer Credit Cards
Balance transfer cards are a specific tool for consolidating and paying down existing credit card debt. They allow you to move balances from other high-interest cards onto one card, usually with a promotional low or 0% rate for a limited time.
Best for: People with existing credit card debt who want to pay it off faster without accumulating additional interest.
Watch out for: Balance transfer fees (commonly a percentage of the amount transferred) and the requirement to pay off the balance before the promotional period ends.
6. Student Credit Cards
Designed for college students with little or no credit history, these cards typically come with lower credit limits and more accessible approval requirements. Some also include modest rewards or cash back to encourage responsible use.
Best for: Students building credit for the first time, ideally alongside financial education about how interest and credit utilization work.
Watch out for: Overspending relative to income, since limits are low but so is the margin for error early in a credit history.
7. Secured Credit Cards
Secured cards require a cash deposit that typically becomes your credit limit. Because the issuer holds this deposit as collateral, secured cards are far easier to get approved for than unsecured cards, making them a common starting point for people with no credit history or those rebuilding credit after financial setbacks.
Best for: People with poor, limited, or no credit history who need to build or repair credit before qualifying for unsecured cards.
Watch out for: Fees for account maintenance, and make sure the issuer reports your payment activity to the major credit bureaus — otherwise, the card won’t help build your credit.
8. Business Credit Cards
Business credit cards are issued to business owners rather than individuals, and they separate personal and business expenses, which simplifies bookkeeping and taxes. Many include rewards tailored to common business expenses like office supplies, shipping, or advertising.
Best for: Freelancers, small business owners, and entrepreneurs who want to track expenses separately and potentially earn business-relevant rewards.
Watch out for: Personal liability — most business cards for small businesses still require a personal guarantee, meaning you’re personally responsible for the debt.
9. Store (Retail) Credit Cards
Offered by specific retailers, these cards provide discounts, special financing, or loyalty points for purchases at that store. Some function like general credit cards, while others (closed-loop cards) can only be used at the issuing retailer.
Best for: Loyal customers of a particular store who shop there often enough to benefit from the discounts.
Watch out for: Typically high interest rates and limited usability outside the specific retailer.
10. Charge Cards
Technically distinct from traditional credit cards, charge cards require you to pay your full balance every month — there’s no revolving credit or minimum payment option. In exchange, many charge cards offer no preset spending limit and strong rewards programs.
Best for: Disciplined spenders with strong, consistent income who don’t want the temptation of carrying a balance.
Watch out for: Late payment penalties can be steep, since the “pay in full” requirement is strictly enforced.
How to Choose the Right Credit Card for You
With so many types available, narrowing down your choice comes down to a few honest questions:
What’s your credit score range? This determines which cards you’ll realistically be approved for. Checking your credit score before applying can save you from unnecessary hard inquiries.
Do you plan to carry a balance? If so, prioritize low interest rates over rewards, since interest charges will likely outweigh any points or cash back you earn.
What do you spend the most on? Match a card’s reward categories (groceries, gas, travel, dining) to your actual spending habits, not to what sounds appealing in an ad.
Are you trying to build credit or maximize rewards? These are different goals that call for different card types — a secured card serves one purpose, a premium travel card serves another.
Can you justify an annual fee? Only worth it if the rewards or perks you’ll actually use exceed the fee’s cost over a year.
Final Thoughts
There’s no single “best” credit card — only the card that’s best suited to your credit profile, spending habits, and financial goals. Someone building credit from scratch needs a very different card than someone chasing airline miles or paying down debt. Take the time to match the card type to your actual situation, read the terms carefully, and you’ll be in a much stronger position to use credit as a tool rather than a liability.
This article is for informational purposes only and does not constitute financial advice. Always review the specific terms, interest rates, and fees of any credit card directly with the issuer before applying.